 By
Most FIRE writing starts with one big number: enough to cover everything you spend, for good. For most people that is twenty years away. Lean FIRE asks a smaller question first: how much would it take to cover only the spending you couldn’t cut?
Lean FIRE is the point where your investments could pay for the essentials (a roof, food, heating, getting around) indefinitely, even if your income stopped tomorrow. You might not want to live on that. You no longer have to fear it.
In this post I go through what Lean FIRE means, how to work out your number, how to split a year of real spending into what you need and what you choose, a worked example with real figures, and how Lean FIRE compares with Fat FIRE. It is one of the types of FIRE, and the one that needs no income at all.
What Lean FIRE means
In the FIRE community, Lean FIRE usually means retiring early on a small total budget: living frugally, for good, on a portfolio sized to that budget. It is often quoted as spending under $40,000 a year, sometimes $25,000 for a single person. That dollar figure is a convention from American forums, not a rule, and it says nothing about your rent, your city or your household.
This post measures Lean FIRE differently, and more usefully: as your Survival spending, the part of what you spend today that you would still pay if you had to cut back hard. That is a number you can find in your own statements, and it answers a real question: could my investments keep me going if work stopped?
How to work out your Lean FIRE number
You need one figure: what your Survival spending comes to in a month. Your portfolio has to cover it for as long as you live off it. Under the 4% rule, a portfolio can pay out about 4% of its value a year, rising with inflation, and last at least thirty years. So:
Lean FIRE number = monthly Survival spending × 12 ÷ 4%
Dividing by 4% is the same as multiplying by 25: a year of Survival spending, twenty-five times over.
The 4% figure comes from William Bengen’s 1994 study of historical US returns, and was tested again in the 1998 Trinity study by Cooley, Hubbard and Walz. It is a rule of thumb, not a guarantee, but it is the one most FIRE planning starts from, and the one I use throughout this post.
The hard part isn’t the maths. It is deciding which of your spending counts as Survival.
Splitting your spending: Survival and Non-essential
Every line you spend falls into one of two groups:
- Survival: what you would still pay if your income stopped and you had to make it last. The cheapest version of your life you would accept for years, not a month.
- Non-essential: everything above that. Not wasteful, just chosen.
You don’t need an app for this. A spreadsheet with your bank’s statements is enough.
Start from the last 12 months, not a budget
Download the statements for the past 12 months from every account you spend from. Use what you actually spent, not what you plan to spend: budgets leave out the car repair, the dentist and the annual insurance bill, and those are exactly the costs a Lean number has to carry. Twelve months catches each of them once. Add up each category over the year and divide by 12.
The usual split
| Category | Usual group | Why |
|---|---|---|
| Rent or mortgage interest | Survival | You need somewhere to live |
| Utilities and heating | Survival | Electricity, water, gas and heating don’t stop |
| Groceries | Survival | Food you cook at home |
| Insurance | Survival | Home, health and liability cover protect what you have |
| Phone and internet | Survival | The cheapest plan that works; the rest is a choice |
| Getting to work, the doctor, the shops | Survival | Public transport, or the running costs of a car you need |
| Healthcare and medicines | Survival | Not optional when you need it |
| Eating out and takeaways | Non-essential | Groceries already cover food |
| Holidays and travel | Non-essential | Worth it, but you could pause it |
| Subscriptions and streaming | Non-essential | Each one can be cancelled |
| Hobbies, sport and going out | Non-essential | The things that make life good, and that you choose |
| Clothes beyond replacing what wears out | Non-essential | Replacing basics is small; the rest is taste |
| Gifts and giving | Non-essential | Generous, and in your control |
The edge cases
- Groceries vs eating out. Food is Survival; how you eat it isn’t. Supermarket shopping goes to Survival, restaurants and delivery to Non-essential, even when the delivery is a Tuesday night’s dinner.
- Transport. A bus pass or the fuel, insurance and servicing of a car you need is Survival. A second car, or a nicer one than the job needs, is the Non-essential part.
- Insurance. Cover that protects your home, your health or your income is Survival. Gadget insurance and extended warranties are Non-essential.
- A mortgage: interest vs principal. The interest is a cost, so it is Survival. The principal isn’t spending at all: it lowers what you owe, so it is closer to saving. Leave it out of both groups. (Once the mortgage is paid off, your Survival spending drops by the interest, and your Lean number with it.)
- Childcare and school costs. Survival if you need them to work or by law, Non-essential if they are extras.
The rule for anything else
For a line you can’t place, ask: if my income stopped for good and I had to make my portfolio last, would I still pay this, at the cheapest version I’d accept? The cheapest version is Survival and anything above it is Non-essential. If you still can’t decide, put it in Survival. That makes your Lean number a little bigger and your safety net a little more honest.
A worked example
Say you are 35. You take home €3,500 a month and spend €2,240 of it, so you save €1,260, a savings rate of 36%. You have €80,000 invested, and it grows 5% a year after inflation.
A year of statements, sorted with the table above, splits the €2,240 like this:
| Survival | A month | Non-essential | A month |
|---|---|---|---|
| Rent | €850 | Eating out | €220 |
| Groceries | €280 | Holidays | €250 |
| Utilities, phone and internet | €130 | Hobbies and subscriptions | €120 |
| Transport | €80 | Clothes and gifts | €100 |
| Insurance | €60 | Everything else | €150 |
| Total | €1,400 | Total | €840 |
Lean FIRE covers the Survival spending: €1,400 × 12 ÷ 4% = €420,000. At your current savings rate you reach it at about 48.
Full FIRE covers all of it: €2,240 × 12 ÷ 4% = €672,000, reached at about 54. Lean FIRE comes six years earlier, and from 48 on a lost job is no longer a threat to the roof over your head.
How you split the spending moves the date a long way:
| Survival spending a month | Lean FIRE number | Reached at about |
|---|---|---|
| €1,000 | €300,000 | 44 |
| €1,200 | €360,000 | 46 |
| €1,400 | €420,000 | 48 |
| €1,600 | €480,000 | 50 |
| €1,800 | €540,000 | 51 |
| €2,240 (full FIRE) | €672,000 | 54 |
Starting at 35 with €80,000 invested, saving €1,260 a month (€15,120 a year), 5% real return, 4% withdrawal rate. The age is when €80,000 × 1.05ⁿ + €15,120 × (1.05ⁿ − 1) ÷ 0.05 reaches the number, to the nearest year.
Every €100 a month of Survival spending adds €30,000 to the target, about a year at this savings rate. That is why the split is worth doing carefully: put a restaurant habit in Survival and you push your safety net out by years; leave the car insurance out and you have a number that wouldn’t hold.
Lean FIRE vs Fat FIRE
Lean and Fat FIRE sit at either end of the same line. Both use the 4% rule; they differ in how much spending they ask the portfolio to cover.
Lean FIRE covers your Survival spending only. The life you could fall back on.
Fat FIRE covers more than all of your spending today. A portfolio with room to spare for travel, giving, and the costs you can’t plan. Lume sets it at a multiple of your whole spending, 1.5× by default.
With the example’s figures:
| Lean FIRE | Fat FIRE | |
|---|---|---|
| Spending it covers | Survival only | All spending × 1.5 |
| A month | €1,400 | €3,360 |
| Number | €420,000 | €1,008,000 |
| Reached at about | 48 | 60 |
The gap between them is two things: your Non-essential spending, which separates Lean from full FIRE, and the multiplier, which separates full FIRE from Fat. The first is in your control every month; the second is how much margin you want.
You will see both defined in US dollars elsewhere: Lean under $40,000 a year, Fat over $100,000. Those thresholds don’t travel to Europe. Rent in Lisbon, a pension in Germany, healthcare that doesn’t come with a job: the same lifestyle costs a different amount, and a fixed figure tells you nothing about yours. Measuring both from your own spending does.
What Lean FIRE buys you
Lean FIRE doesn’t mean you stop working. Most people who reach it keep going, because they want the life their Non-essential spending pays for.
What changes is the risk. A layoff becomes an inconvenience rather than a crisis: your portfolio could keep the essentials paid while you look, for as long as it takes. And career risks become affordable: a pay cut for better work, a year off, starting something of your own. The worst case is the Survival life, and you have already paid for it.
It also comes years before full FIRE (six in the example), so it is a milestone you can watch fill while the big number still feels far away. And unlike Barista FIRE, which can come sooner, it doesn’t depend on finding part-time work: the portfolio covers the essentials on its own.
Tracking it in Lume
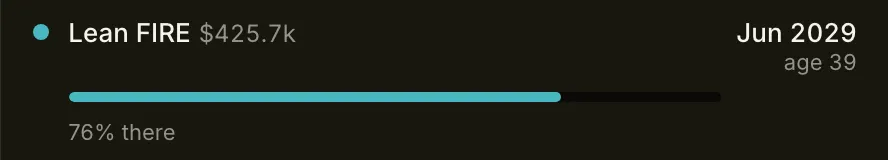
I track this in Lume, a private FIRE tracker for Mac and iPhone. When I close a month, each line I categorise goes into a category in the Survival or the Non-essential group, so the split above happens as part of the close rather than once a year in a spreadsheet. The Lean FIRE milestone on the dashboard is worked out from that Survival spending at my withdrawal rate, and with a scenario set up it shows the date and age I could reach it.
Where to go from here
Lean FIRE is the milestone where losing your income stops being frightening. To work out yours you need one honest figure, your Survival spending from a year of real statements, and one line of maths.
If you could live on a part-time job plus your portfolio, Barista FIRE may come sooner still: for the same person, with €1,200 a month of part-time income, it is €312,000 at about 45. Types of FIRE covers Lean, Barista, Coast, FIRE and Fat side by side.
This post is general information, not financial advice. The 4% rule is based on historical returns, which aren’t a promise about future ones.
General information, not financial advice. Your taxes, pension and circumstances will differ from the examples here. More on that.